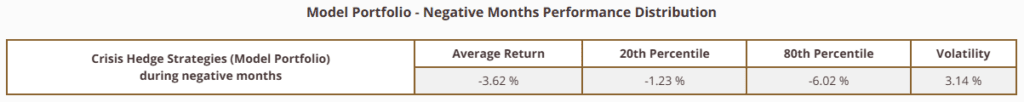Most systematic trading strategies are pro cyclical by nature. They perform best when markets trend higher and volatility remains contained. During broad market expansions, equity risk premia, momentum and trend following approaches tend to generate stable positive returns.
However, during market crises or extended bear markets, many of these strategies become synchronized. Correlations increase, volatility spikes and traditional diversification weakens. In such environments, portfolios built primarily from pro cyclical strategies may experience simultaneous drawdowns. This creates a structural need for strategies that behave differently during stress periods.
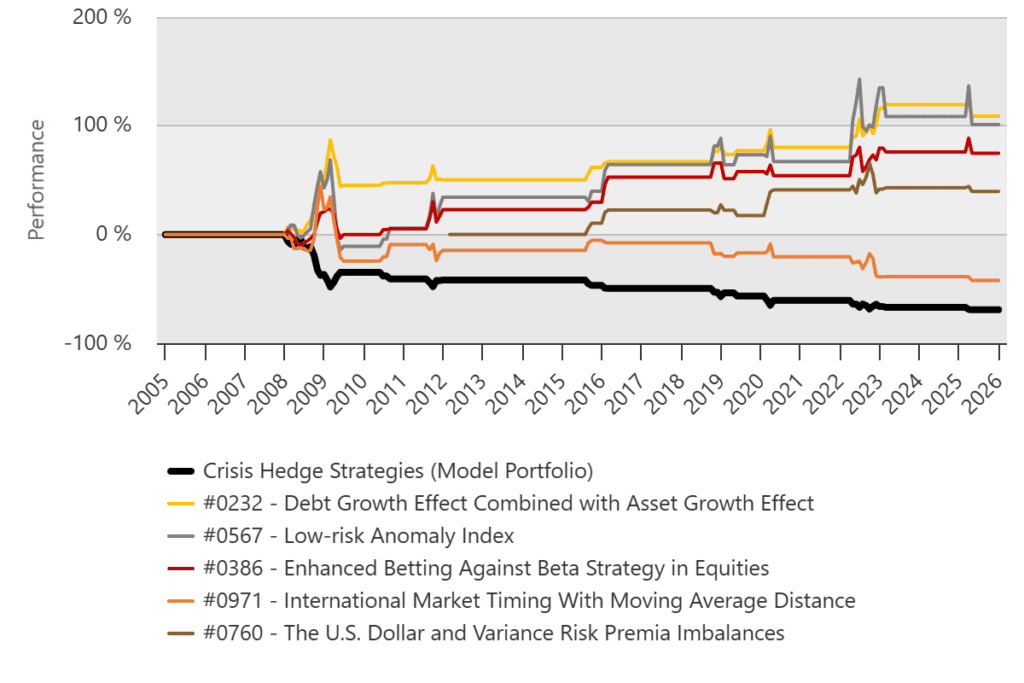
Crisis hedge strategies represent such a subset. They are designed to deliver diversification benefits specifically when equity markets decline. Because of their specialized behavior, they represent only a small fraction of the overall strategy universe.
This analysis demonstrates how crisis hedge strategies can be identified, evaluated and integrated into a model portfolio using the Quantpedia Pro framework.
Three Ways to Work with Crisis Hedge Strategies
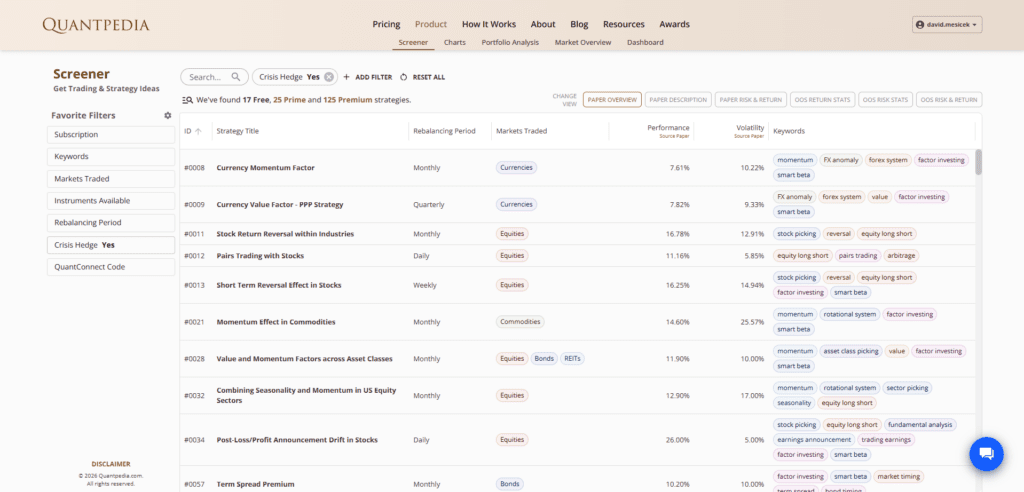
Within the Quantpedia framework, crisis hedge strategies can be incorporated using three complementary approaches.
The second approach relies on the Crisis Hedge Portfolio Analysis report, which automatically scans the database and suggests strategies based on downside correlation and regime dependent characteristics.
The third approach involves portfolio construction through the Optimization report. In this case, users manually select a pool of candidate strategies, add them into a benchmark universe and allow the optimization engine to determine the most efficient allocation.
This designation is not based on marketing descriptions but on empirical behavior during stress regimes. Information about the crisis hedge behavior is extracted from source research papers and strategies are evaluated based on their performance during bear markets, negative equity months and their correlation characteristics relative to traditional equity exposure.
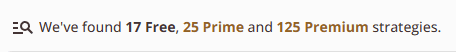
At the time of analysis, approximately 167 strategies, representing around 12% of the database, are classified as crisis hedge. This confirms that truly defensive approaches are relatively scarce within the broader systematic universe.
Baseline Equity Portfolio
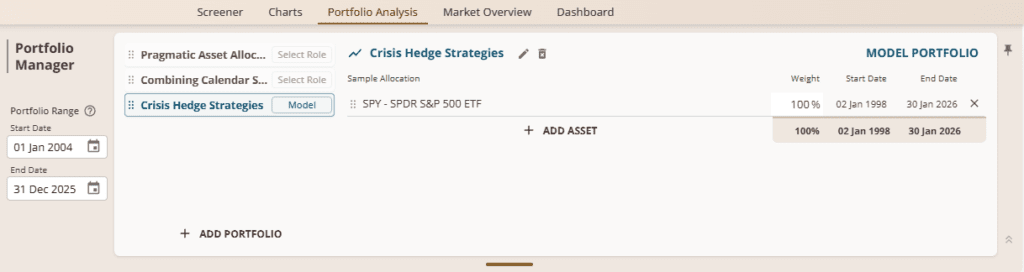
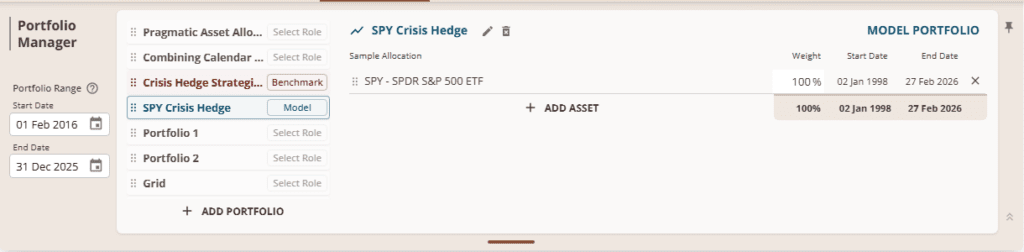
To evaluate the impact of crisis hedge integration, we first construct a baseline portfolio consisting of 100 percent SPY exposure.
This portfolio serves as the reference case for all subsequent comparisons.
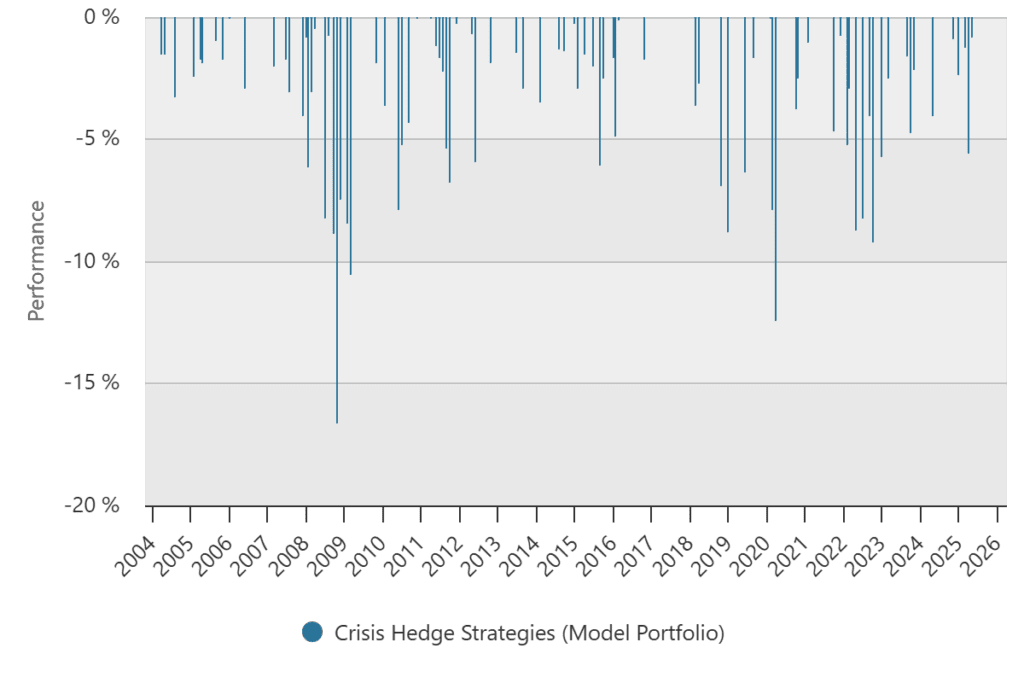
The baseline portfolio shows expected downside clustering and volatility expansion during these periods.
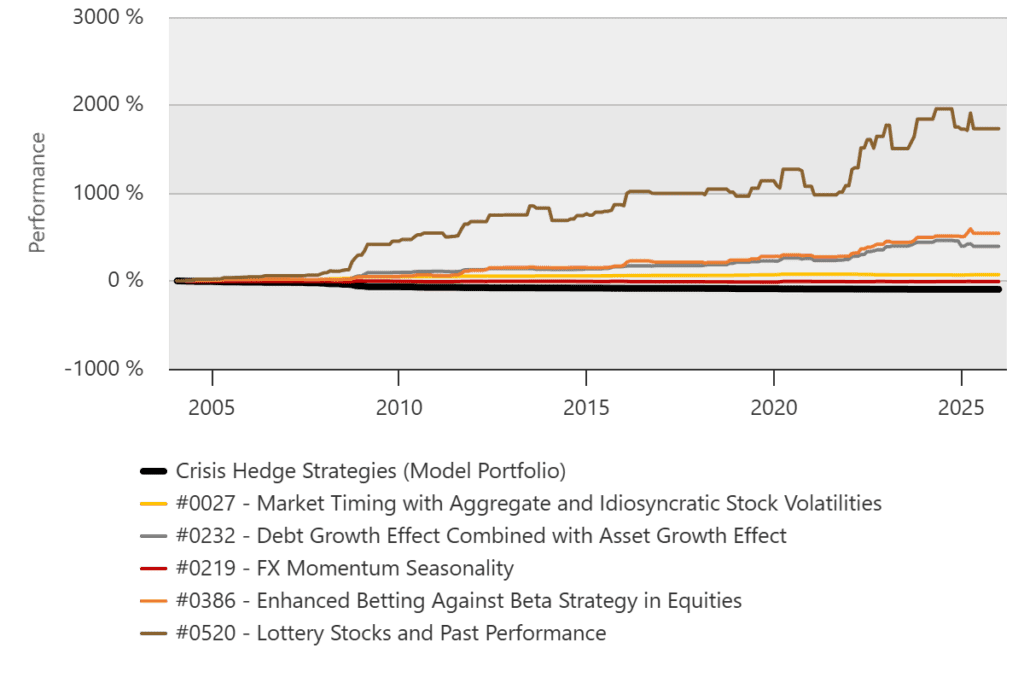
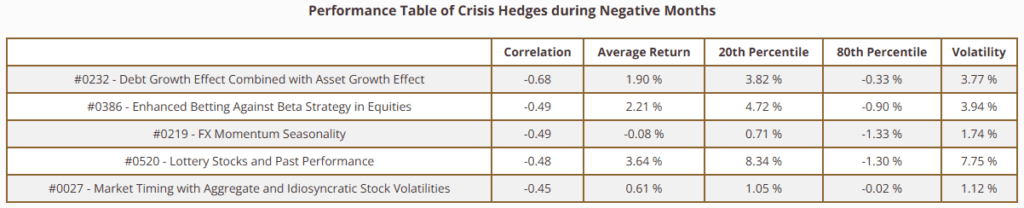
The report automatically scans the database and identifies strategies that historically delivered favorable characteristics during such stress periods.
Selected strategies exhibit negative correlation to equities and positive average returns during negative months.
Behavior During Bear Market Regimes
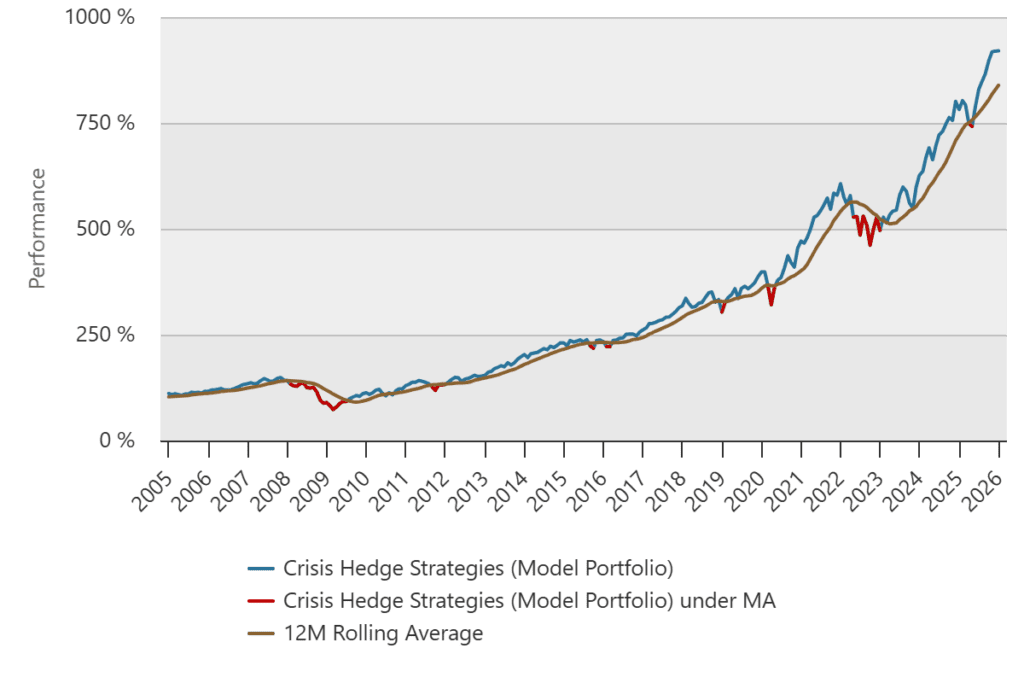
Beyond isolated negative months, extended bear market regimes are identified using a 12 month moving average filter.
Crisis hedge strategies maintain defensive properties during prolonged downturns.
Optimization Framework
The third approach uses the Optimization report to identify which crisis hedge strategies improve the performance of an equity based portfolio.
The workflow consists of three simple steps.
First, create a model portfolio that represents the base allocation. In this example, the model portfolio consists of 100 percent exposure to SPY, which serves as a proxy for the US equity market.
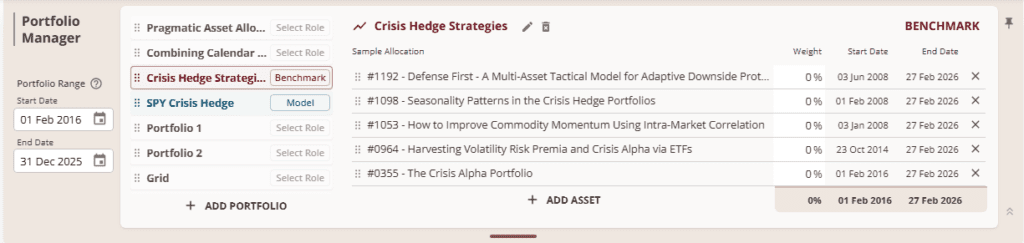
Next, create a benchmark portfolio that contains the crisis hedge strategies you want to evaluate. These strategies define the candidate pool that will be tested against the model portfolio.
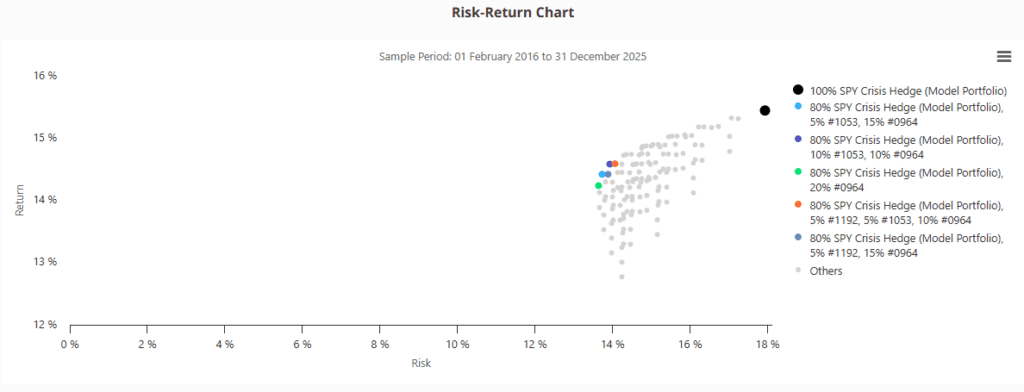
Once both portfolios are defined, the Optimization report evaluates how strategies from the benchmark interact with the model portfolio. The optimization engine systematically tests combinations of benchmark strategies and determines which allocations improve the portfolio’s overall return to risk characteristics.
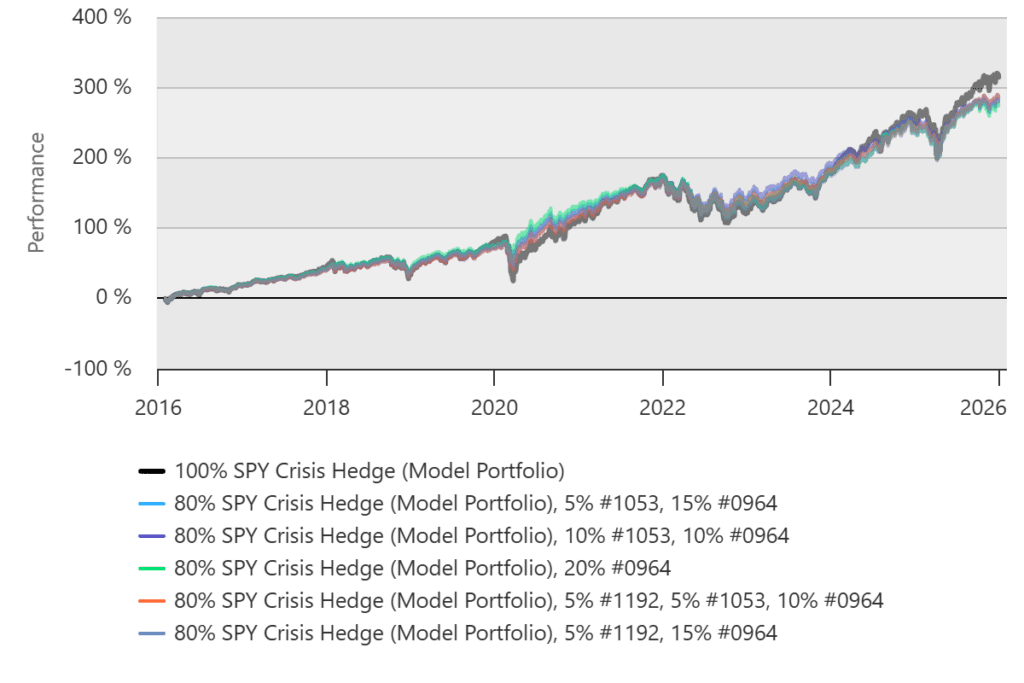
The optimization results indicate that introducing a modest allocation to crisis hedge strategies can significantly improve portfolio efficiency. Several tested combinations shift the portfolio upward in the risk return space while simultaneously reducing overall volatility.
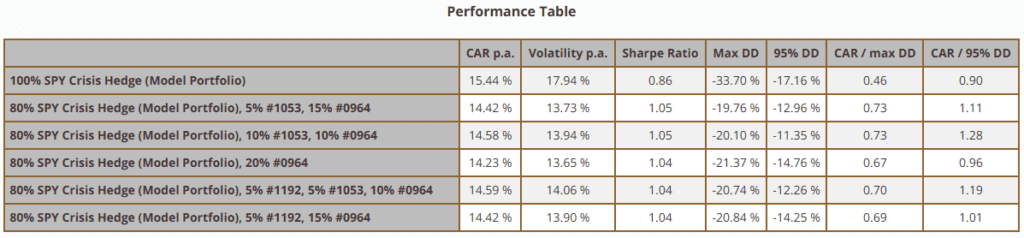
Performance comparison confirms that optimized allocations maintain comparable long term returns while reducing drawdown intensity and improving risk adjusted metrics.
The table highlights the improvement in Sharpe ratio and the reduction in maximum drawdown when crisis hedge strategies are included alongside the equity allocation.
Importantly, the optimization framework is flexible. The benchmark universe does not need to contain only crisis hedge strategies. ETFs, alternative assets or proprietary strategies can also be included, allowing investors to search for allocations that improve the overall portfolio efficiency.
Conclusion
Crisis hedge strategies represent a structurally distinct subset of systematic approaches. While they do not eliminate risk, they materially improve diversification and drawdown characteristics when integrated efficiently. Using Quantpedia’s analytical framework, from screener identification through regime testing and portfolio optimization, investors can construct crisis aware allocations that enhance long term risk adjusted performance while maintaining structural robustness across market cycles.
Author: David Mesíček, Junior Quant Analyst, Quantpedia
Do you want algorithmic access to the full Quantpedia database via the API? Subscribe to Quantpedia Pro, ask for an API key, and explore the in/out-of-sample statistics, source academic papers, and code snippets — ideal for quantitative research, systematic trading workflows, and AI model training.
Are you looking for historical data or backtesting platforms? Check our list of Algo Trading Discounts.
[s]Quantpedia[/s] is The Encyclopedia of Quantitative Trading Strategies
We’ve already analysed tens of thousands of financial research papers and identified more than 700 attractive trading systems together with hundreds of related academic papers.